Foreign demand rising
International buyers increasingly support new-build sales as domestic demand softens. AREA surveys show foreign purchases recovering to pre-pandemic levels, led by Chinese, Myanmar, and Indian nationals.
 Marketing Studio
Country story · Agent brief
Market context for foreign condominium buyers
Atmosphere
Talking Path
Share these headlines with buyers — then open a deep dive below for the full path.
International buyers increasingly support new-build sales as domestic demand softens. AREA surveys show foreign purchases recovering to pre-pandemic levels, led by Chinese, Myanmar, and Indian nationals.
BTS and MRT expansion continues to reshape micro-markets. Prime Sukhumvit commands prestige; outer BTS corridors (On Nut, Bang Na, Rama 9) offer stronger yields at lower entry prices.
CBRE and JLL note yield compression in prime CBD stock (often 3.5–5%) while midtown districts can reach 5–7% gross. Luxury segments target capital preservation; mid-market targets cash flow.
Condominiums remain the primary freehold route for foreigners. Purchases require quota availability, foreign-currency inward remittance, and Land Department registration.
Deep Dives
Unlocking Demand, Legal Frameworks, and High-Yield Districts
Supply, Demand & Foreign Participation
Bangkok's condominium market is one of Southeast Asia's deepest and most liquid. Industry surveys (AREA, REIC) show foreign buyers accounting for roughly 18–24% of new developer sales in recent years — propping up volume as local end-user demand cools. Prime rents have continued to rise (JLL cites ~8% YoY growth for luxury stock in 2025), while transaction values can fluctuate with buyer nationality mix and global economic conditions.
Gateway City Fundamentals
Bangkok is Thailand's economic engine and a regional hub for business, aviation, healthcare, and tourism. For property investors, it offers scale (thousands of projects), professional agency infrastructure, and relative affordability versus Singapore or Hong Kong — with a large renter pool of expats, students, and domestic professionals.
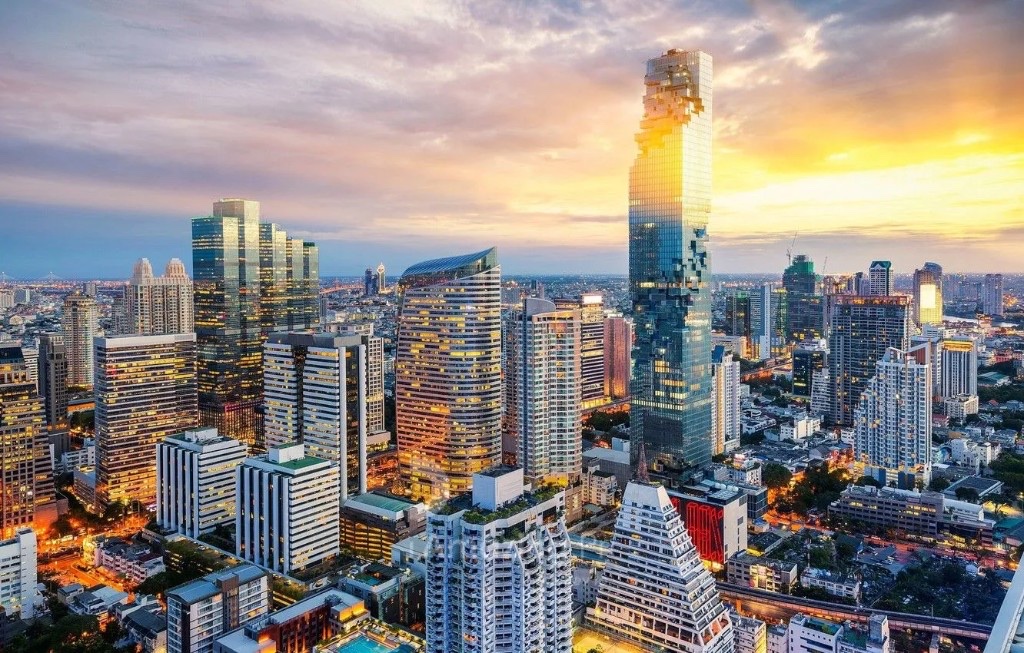
ASEAN hub for multinationals, Japanese trading houses, and Chinese tech firms. Consistent demand for quality rental stock near BTS/MRT.
International schools, private hospitals, dining, and wellness attract long-stay residents — not just tourists. Thonglor, Ari, and Sathorn remain expat magnets.
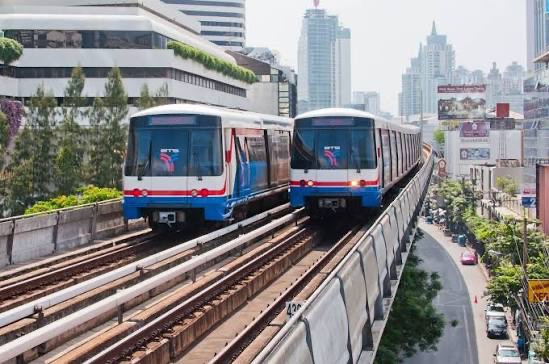
Existing BTS/MRT network plus planned extensions influence micro-market pricing. Transit proximity remains the strongest price driver after build quality.
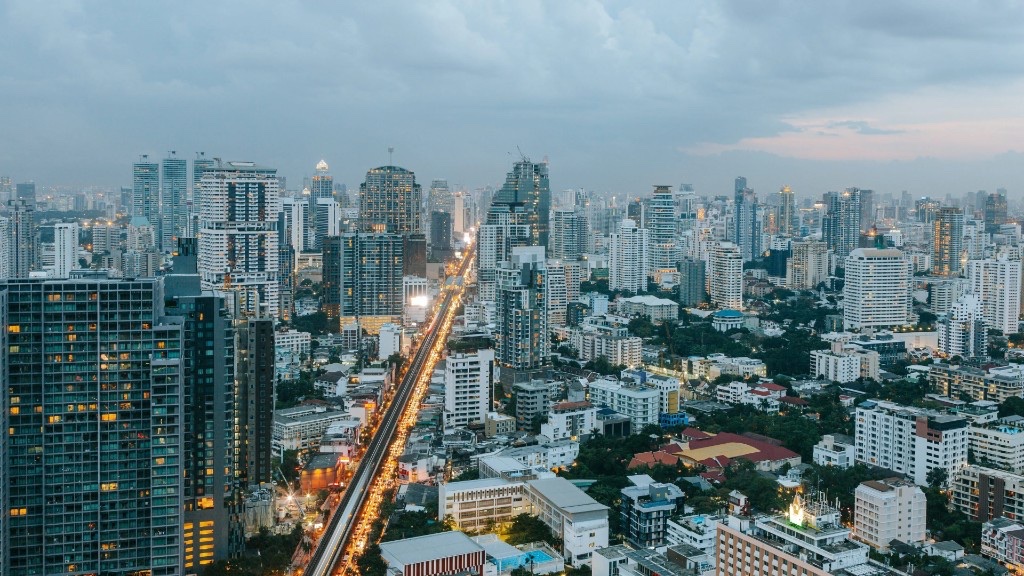
Prime Bangkok entry prices remain below regional peers on a per-sqm basis. Mid-market condos (THB 4–10M) form the core foreign-investor sweet spot.
Corporate leases, digital-nomad visas (DTV), and domestic young professionals sustain rental demand. Vacancy risk is lower in established transit corridors.
Established listed developers (AP, Sansiri, Noble, Ananda, etc.) offer completed stock with professional juristic person management — important for resale liquidity.
Yields, Districts & Buyer Checklist
There is no single 'Bangkok yield' — outcomes depend on district, building age, and price point. Industry guides (CBRE, Cushman & Wakefield, Global Property Guide) consistently show prime Sukhumvit (Asoke, Phrom Phong, Thonglor) trading yield for prestige, while On Nut, Bang Na, Rama 9, and Ratchada offer stronger gross returns at lower capital outlay.
Sukhumvit CBD, Silom, Sathorn — lower yields (often sub-5%) but strongest branding, liquidity, and long-term capital preservation. Suited to owner-occupiers and wealth holders.
On Nut, Bang Na, Bearing, Rama 9 — higher gross yields (5–7%) on smaller tickets. Target Thai professionals and budget-conscious expats near BTS.
Ari, Ekkamai — premium rents for quality units. Yield compression is real; buying decisions should factor furnishing, view, and building reputation.
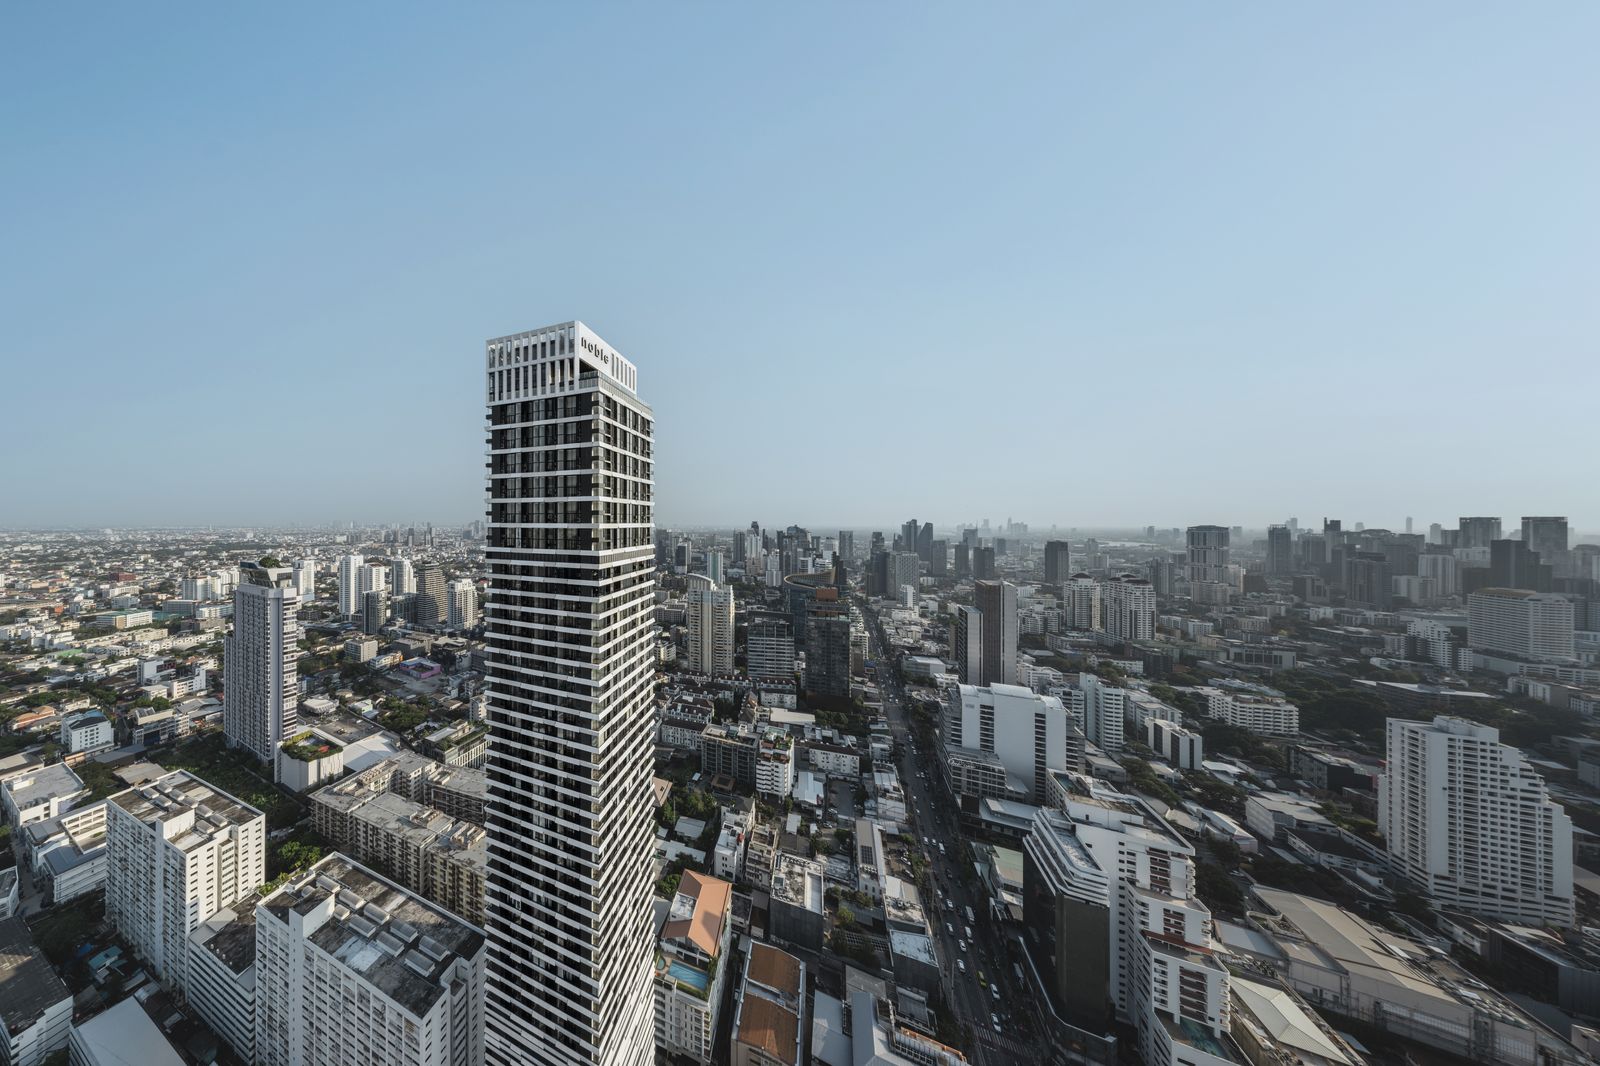
Confirm foreign quota slot, sinking fund balance, common-area fees, actual sold vs advertised pricing, rental comps from 2–3 agencies, and developer track record.
Freehold Condominium Guide
Foreign nationals may own up to 49% of the total sellable area of a registered condominium in freehold. The process is well-established but requires correct fund transfer documentation. Always engage a lawyer for SPA review and quota confirmation before paying a reservation deposit.
Developer or juristic person certifies a foreign quota slot is available for your unit. Quota can fill up in popular buildings — verify in writing.
Purchase funds must be transferred from abroad in foreign currency. The receiving Thai bank issues a Foreign Exchange Transaction (FET) form — required at the Land Department.
Sign reservation agreement, then Sale & Purchase Agreement. Review payment schedule, completion date, penalties, and defect liability with legal counsel.
Upon completion, register ownership at the Land Department. Receive your Chanote (title deed) in your name — freehold condominium ownership.
Pay common-area fees, sinking fund contributions, and personal income tax on rental income if letting. Annual juristic person meetings govern building management.
On resale to another foreigner, a new FET may be required. Transfer fees and withholding tax apply — factor into exit planning.